How to Build a Simple Credit Card Stack for Everyday Spending
A useful credit-card stack is not a collection. It is a small system in which each card has one clear job, the fees fit the household’s real spending, and the setup remains easy to use.
By StaxxRewards Editorial. Published by Staxx Media, Inc.
By StaxxRewards Editorial. Published by Staxx Media, Inc.
What to know
Start with how you already spend, not with a list of advertised card benefits.
Give each card a distinct role so you can remember which one to use.
Compare net value after fees, caps, exclusions, and realistic redemption assumptions.
If you expect to carry a balance, reducing interest cost matters more than earning rewards.
What a simple card stack means
A credit-card stack is a small group of cards designed to work together. One card might cover the category where most of your money goes, another might support a travel goal, and a third might earn a steady rate on purchases that do not fit a bonus category.
The stack is useful only if every card has a job. Adding another card because it has a large welcome offer or a long benefit list can increase fees and tracking without improving the everyday setup.
For many people, one or two cards are enough. A third card should solve a specific gap rather than create a new chore.
Start with spending, goals, and constraints
Before looking at products, collect three pieces of information.
Your recurring eligible spending
Review several months of statements and group purchases into broad categories such as groceries, dining, gas or charging, transit, travel, and everything else. Use actual spending, not the amount you hope to spend.
Remember that rewards categories depend on issuer definitions and merchant coding. A merchant that sells groceries may be classified as a warehouse club or superstore, and a restaurant inside a hotel may post as a hotel purchase.
Your preferred reward
Decide whether you want cash back, travel rewards, or a mix. Cash back is usually easier to value. Points or miles may offer several redemption methods, but the value can vary by program and booking.
Do not assign a point value simply because a blog or calculator uses it. Use the value available through the redemption you are reasonably likely to make.
Your complexity limit
Be honest about what you will track. Rotating categories, enrollment deadlines, spending caps, transfer partners, and statement credits all require attention. A theoretically stronger setup can be worse in practice if you forget which card to use or buy things only to trigger a benefit.
Give each card one clear role
A three-card stack can use the following structure, but the labels are illustrative rather than product recommendations.
Role | Job | Question to answer |
|---|---|---|
Card A: Primary | Earns more in one or two major eligible spending categories | Does the category definition and cap match my real spending? |
Card B: Secondary | Supports a specific goal, such as travel, without duplicating Card A | Will I use the redemption program and justify any fee? |
Card C: Tertiary | Covers purchases outside the other cards’ bonus categories | Is the fallback rate broad and easy to redeem? |
If Cards A and B reward the same spending and serve the same goal, one of them may be unnecessary. If Card C’s only purpose is a small improvement on occasional purchases, the added account may not be worth managing.
Read the sample stack correctly
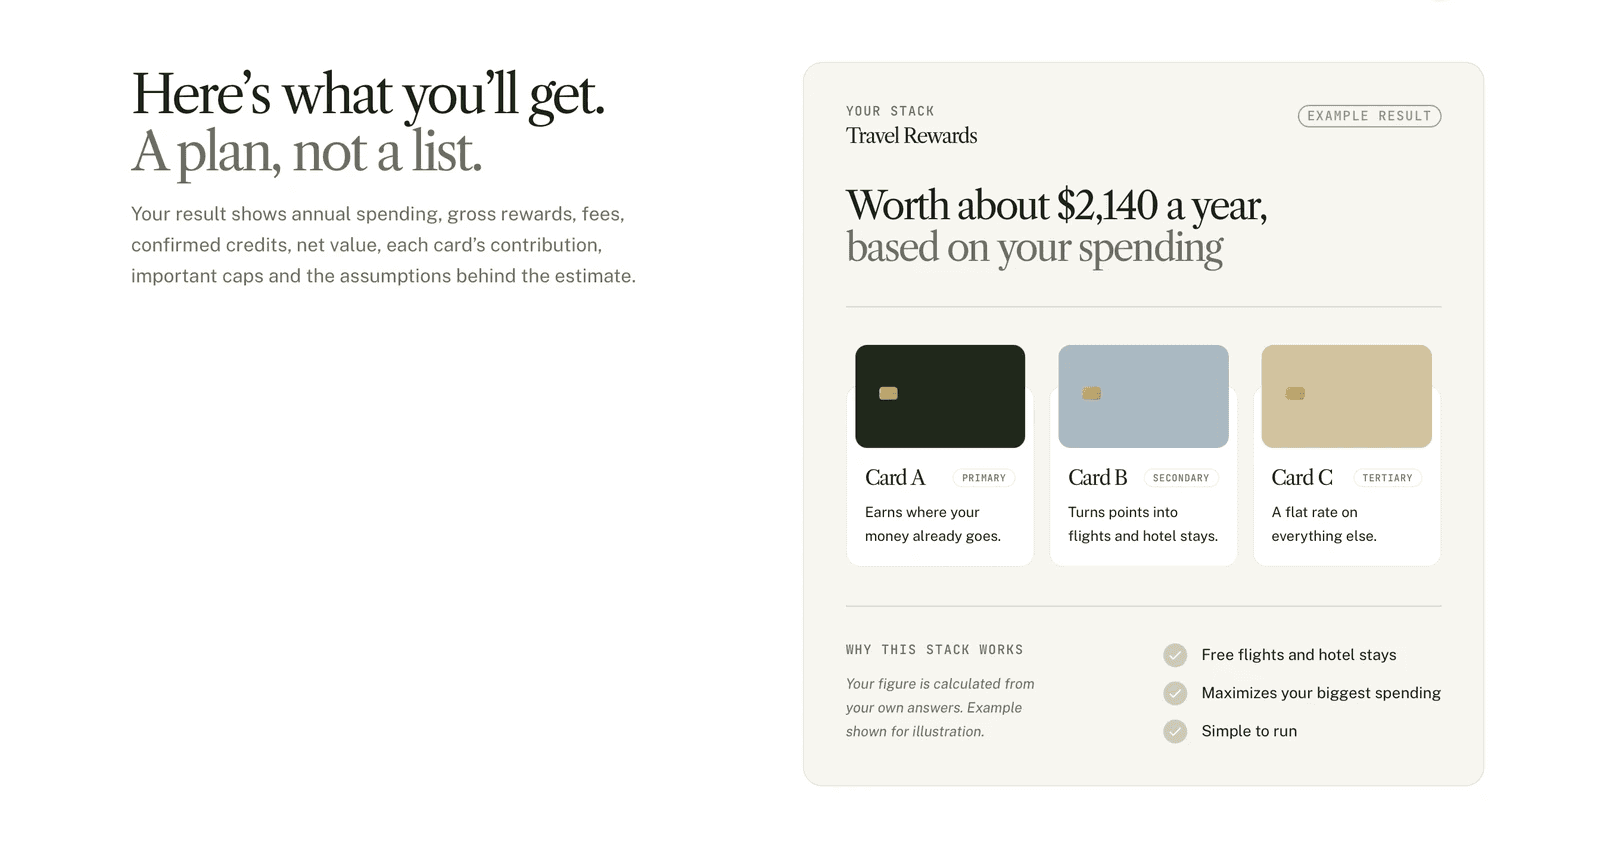
Figure 1. Illustrative three-card stack. Card A, Card B, Card C, and the displayed $2,140 annual value are placeholders—not product recommendations, typical results, or guaranteed outcomes.
The sample result shows the intended structure: a primary, secondary, and tertiary card with distinct jobs. “Card A,” “Card B,” and “Card C” are placeholders. The displayed estimate of $2,140 is an example interface value based on unstated sample inputs; it is not a typical result, a promise, or a recommendation.
Any published result should show the spending assumptions, earn rates, caps, annual fees, credits actually counted, redemption assumptions, and each card’s contribution so the reader can audit the estimate.
Calculate net value before adding a card
First divide annual spending into non-overlapping slices by category and by any applicable cap. For cash back, a basic annual estimate is:
eligible spending × applicable cash-back rate = estimated gross cash back
If a bonus rate has a cap, calculate the spending below and above the cap separately. For points or miles, show both the points earned and the redemption value assumed rather than presenting one unexplained dollar figure.
Add only statement credits or benefits the reader realistically expects to use, and value them at replacement value rather than automatically at face value. Keep a welcome offer separate from recurring annual value.
Then subtract costs:
ongoing net value = recurring reward value + realistically usable recurring benefits − recurring fees and incremental costs
Do not count a statement credit at face value unless it replaces a purchase you would otherwise make. Buying an unneeded $75 item to use a $75 credit does not create $75 of useful value.
Check the operating rules
Before adding any card, review:
the issuer’s current category definitions and merchant-coding examples;
spending caps and when they reset;
enrollment or activation requirements;
the base earn rate outside bonus categories;
the annual fee and any authorized-user fees;
redemption minimums, restrictions, and expiration rules;
whether rewards can be combined between the cards;
foreign transaction fees if relevant; and
the payment system you will use to avoid missed due dates.
Issuer terms control. A marketplace or third-party processor can prevent a purchase from being identified as expected, even when the item itself seems to fit a bonus category.
Keep the stack easy to operate
Use one short rule per card, such as “groceries and dining,” “travel purchases,” and “everything else.” Put recurring charges on the intended card, enable account alerts, and review rewards after unfamiliar merchants post.
Recalculate the stack at least once a year and whenever a fee, reward rate, cap, benefit, or spending pattern changes. If a card no longer has a distinct job, simplify the setup rather than inventing a reason to keep it.
When rewards should not be the priority
The Consumer Financial Protection Bureau explains that consumers who carry revolving balances often pay far more in interest and fees than they receive in rewards. Many issuers calculate interest daily. A purchase grace period is not required, can be lost under the card agreement, and generally applies only when its conditions are met; cash advances generally do not receive one.
Rewards should not drive the decision if you expect to carry a balance. Prioritize APR, repayment cost, and paying the statement balance in full by the due date when a purchase grace period applies. A legitimate promotional rate can change short-term cost, so check the controlling agreement instead of relying on a general rule.
Before you act
Check each issuer’s current rates, fees, eligibility rules, card agreement, and rewards terms. Applying is a separate decision, and approval and account terms are determined by the issuer.
StaxxRewards provides educational information and illustrative estimates, not individualized financial advice. Reward value depends on eligible spending, card terms, fees, and redemption choices.
Sources
Consumer Financial Protection Bureau: How credit-card interest is calculated — daily interest, grace periods, and paying in full. Reviewed August 11, 2026.
Consumer Financial Protection Bureau: What is a credit-card grace period? — purchase grace periods, conditions, and cash-advance treatment. Reviewed August 11, 2026.
https://www.consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47/
Consumer Financial Protection Bureau: Consumer frustrations with rewards programs — revolving-balance costs relative to rewards. Reviewed August 11, 2026.
Visa Merchant Data Standards Manual, April 2026 — merchant category code framework. Reviewed August 11, 2026.
https://usa.visa.com/content/dam/VCOM/download/merchants/visa-merchant-data-standards-manual.pdf
Mastercard Rules, effective June 2, 2026 — acquirer responsibility for merchant classification. Reviewed August 11, 2026.
https://www.mastercard.com/content/dam/mccom/shared/business/support/rules-pdfs/mastercard-rules.pdf
Chase Rewards Category FAQ — category definitions and merchant-classification examples. Reviewed August 11, 2026.
https://www.chase.com/personal/credit-cards/rewards-category-faq
American Express Rewards Information and FAQs — eligible purchases, merchant codes, and third-party processing. Reviewed August 11, 2026.
https://www.americanexpress.com/en-us/benefits/rewards/rewards-information/
Corrections and updates
If you believe a statement is incorrect, email info@staxxrewards.com with the page URL and an official source. StaxxRewards reviews material corrections and time-sensitive product information.
FAQ
How many cards should be in a simple stack?
Use the smallest number that gives each card a clear job. One or two may be sufficient; a third should fill a meaningful gap.
Should every card earn a different kind of reward?
No. The important distinction is the role, not the currency. Two cash-back cards can work together if one covers a useful category and the other provides a broad fallback rate.
Is the screenshot’s $2,140 estimate realistic?
It cannot be evaluated without the underlying spending, rates, caps, fees, credits, and redemption assumptions. It should be treated only as an illustrative interface example.
What to know
Start with how you already spend, not with a list of advertised card benefits.
Give each card a distinct role so you can remember which one to use.
Compare net value after fees, caps, exclusions, and realistic redemption assumptions.
If you expect to carry a balance, reducing interest cost matters more than earning rewards.
What a simple card stack means
A credit-card stack is a small group of cards designed to work together. One card might cover the category where most of your money goes, another might support a travel goal, and a third might earn a steady rate on purchases that do not fit a bonus category.
The stack is useful only if every card has a job. Adding another card because it has a large welcome offer or a long benefit list can increase fees and tracking without improving the everyday setup.
For many people, one or two cards are enough. A third card should solve a specific gap rather than create a new chore.
Start with spending, goals, and constraints
Before looking at products, collect three pieces of information.
Your recurring eligible spending
Review several months of statements and group purchases into broad categories such as groceries, dining, gas or charging, transit, travel, and everything else. Use actual spending, not the amount you hope to spend.
Remember that rewards categories depend on issuer definitions and merchant coding. A merchant that sells groceries may be classified as a warehouse club or superstore, and a restaurant inside a hotel may post as a hotel purchase.
Your preferred reward
Decide whether you want cash back, travel rewards, or a mix. Cash back is usually easier to value. Points or miles may offer several redemption methods, but the value can vary by program and booking.
Do not assign a point value simply because a blog or calculator uses it. Use the value available through the redemption you are reasonably likely to make.
Your complexity limit
Be honest about what you will track. Rotating categories, enrollment deadlines, spending caps, transfer partners, and statement credits all require attention. A theoretically stronger setup can be worse in practice if you forget which card to use or buy things only to trigger a benefit.
Give each card one clear role
A three-card stack can use the following structure, but the labels are illustrative rather than product recommendations.
Role | Job | Question to answer |
|---|---|---|
Card A: Primary | Earns more in one or two major eligible spending categories | Does the category definition and cap match my real spending? |
Card B: Secondary | Supports a specific goal, such as travel, without duplicating Card A | Will I use the redemption program and justify any fee? |
Card C: Tertiary | Covers purchases outside the other cards’ bonus categories | Is the fallback rate broad and easy to redeem? |
If Cards A and B reward the same spending and serve the same goal, one of them may be unnecessary. If Card C’s only purpose is a small improvement on occasional purchases, the added account may not be worth managing.
Read the sample stack correctly
Figure 1. Illustrative three-card stack. Card A, Card B, Card C, and the displayed $2,140 annual value are placeholders—not product recommendations, typical results, or guaranteed outcomes.
The sample result shows the intended structure: a primary, secondary, and tertiary card with distinct jobs. “Card A,” “Card B,” and “Card C” are placeholders. The displayed estimate of $2,140 is an example interface value based on unstated sample inputs; it is not a typical result, a promise, or a recommendation.
Any published result should show the spending assumptions, earn rates, caps, annual fees, credits actually counted, redemption assumptions, and each card’s contribution so the reader can audit the estimate.
Calculate net value before adding a card
First divide annual spending into non-overlapping slices by category and by any applicable cap. For cash back, a basic annual estimate is:
eligible spending × applicable cash-back rate = estimated gross cash back
If a bonus rate has a cap, calculate the spending below and above the cap separately. For points or miles, show both the points earned and the redemption value assumed rather than presenting one unexplained dollar figure.
Add only statement credits or benefits the reader realistically expects to use, and value them at replacement value rather than automatically at face value. Keep a welcome offer separate from recurring annual value.
Then subtract costs:
ongoing net value = recurring reward value + realistically usable recurring benefits − recurring fees and incremental costs
Do not count a statement credit at face value unless it replaces a purchase you would otherwise make. Buying an unneeded $75 item to use a $75 credit does not create $75 of useful value.
Check the operating rules
Before adding any card, review:
the issuer’s current category definitions and merchant-coding examples;
spending caps and when they reset;
enrollment or activation requirements;
the base earn rate outside bonus categories;
the annual fee and any authorized-user fees;
redemption minimums, restrictions, and expiration rules;
whether rewards can be combined between the cards;
foreign transaction fees if relevant; and
the payment system you will use to avoid missed due dates.
Issuer terms control. A marketplace or third-party processor can prevent a purchase from being identified as expected, even when the item itself seems to fit a bonus category.
Keep the stack easy to operate
Use one short rule per card, such as “groceries and dining,” “travel purchases,” and “everything else.” Put recurring charges on the intended card, enable account alerts, and review rewards after unfamiliar merchants post.
Recalculate the stack at least once a year and whenever a fee, reward rate, cap, benefit, or spending pattern changes. If a card no longer has a distinct job, simplify the setup rather than inventing a reason to keep it.
When rewards should not be the priority
The Consumer Financial Protection Bureau explains that consumers who carry revolving balances often pay far more in interest and fees than they receive in rewards. Many issuers calculate interest daily. A purchase grace period is not required, can be lost under the card agreement, and generally applies only when its conditions are met; cash advances generally do not receive one.
Rewards should not drive the decision if you expect to carry a balance. Prioritize APR, repayment cost, and paying the statement balance in full by the due date when a purchase grace period applies. A legitimate promotional rate can change short-term cost, so check the controlling agreement instead of relying on a general rule.
Before you act
Check each issuer’s current rates, fees, eligibility rules, card agreement, and rewards terms. Applying is a separate decision, and approval and account terms are determined by the issuer.
StaxxRewards provides educational information and illustrative estimates, not individualized financial advice. Reward value depends on eligible spending, card terms, fees, and redemption choices.
Sources
Consumer Financial Protection Bureau: How credit-card interest is calculated — daily interest, grace periods, and paying in full. Reviewed August 11, 2026.
Consumer Financial Protection Bureau: What is a credit-card grace period? — purchase grace periods, conditions, and cash-advance treatment. Reviewed August 11, 2026.
https://www.consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47/
Consumer Financial Protection Bureau: Consumer frustrations with rewards programs — revolving-balance costs relative to rewards. Reviewed August 11, 2026.
Visa Merchant Data Standards Manual, April 2026 — merchant category code framework. Reviewed August 11, 2026.
https://usa.visa.com/content/dam/VCOM/download/merchants/visa-merchant-data-standards-manual.pdf
Mastercard Rules, effective June 2, 2026 — acquirer responsibility for merchant classification. Reviewed August 11, 2026.
https://www.mastercard.com/content/dam/mccom/shared/business/support/rules-pdfs/mastercard-rules.pdf
Chase Rewards Category FAQ — category definitions and merchant-classification examples. Reviewed August 11, 2026.
https://www.chase.com/personal/credit-cards/rewards-category-faq
American Express Rewards Information and FAQs — eligible purchases, merchant codes, and third-party processing. Reviewed August 11, 2026.
https://www.americanexpress.com/en-us/benefits/rewards/rewards-information/
Corrections and updates
If you believe a statement is incorrect, email info@staxxrewards.com with the page URL and an official source. StaxxRewards reviews material corrections and time-sensitive product information.
FAQ
How many cards should be in a simple stack?
Use the smallest number that gives each card a clear job. One or two may be sufficient; a third should fill a meaningful gap.
Should every card earn a different kind of reward?
No. The important distinction is the role, not the currency. Two cash-back cards can work together if one covers a useful category and the other provides a broad fallback rate.
Is the screenshot’s $2,140 estimate realistic?
It cannot be evaluated without the underlying spending, rates, caps, fees, credits, and redemption assumptions. It should be treated only as an illustrative interface example.
Take the quiz
Three questions. Two minutes. Your plan, and its dollar value.
Free · No credit check